Invoice Automation Workflow That Gets You Paid Faster
Build an invoice automation workflow that cuts DSO and manual work. A practical blueprint for professional services firms to automate AR end-to-end.
A client invoice is approved, the work is complete, and the team expects payment. Then the due date passes. Someone searches email for the last reminder, someone else checks a spreadsheet, and the project lead asks whether a follow-up might damage the relationship. Cash is delayed while finance reconstructs what happened.
That pattern is common in professional services because billing rarely ends when an invoice is sent. The operating problem is the path from invoice creation to payment, reconciliation, and escalation. An effective invoice automation workflow coordinates that entire path, including trigger logic, client communication, payment options, cash application, and human review.
For firms with $3M–$50M in revenue, the difference is material. The right design can reduce administrative drag without turning client communication into a robotic collections process. The wrong design moves manual work from invoice entry into exception queues, approval chasing, and reconciliation.
Why Invoice Automation Matters for Professional Services Cash Flow
Professional services firms sell judgment, time, and outcomes. They don't ship a standardized product that a customer can scan and pay without context. Invoices may depend on milestones, retainers, time approvals, project codes, reimbursable expenses, or a client's internal procurement process.
That complexity makes AR a client-relationship workflow, not just finance administration. A late invoice follow-up may involve a project manager, account executive, partner, and client approver. If each person uses a different tone or timing, the client receives mixed signals and the firm loses control of the process.
The cost of manual work appears in several places:
- Inconsistent follow-up: One client receives a reminder before the due date, while another hears nothing until the invoice is seriously overdue.
- Spreadsheet dependence: Staff export aging data, copy amounts into trackers, and reconcile those trackers against the accounting system.
- Approval uncertainty: Finance can't tell whether a payment is late because the client hasn't received the invoice, an approver hasn't approved it, or the client is disputing the work.
- Relationship risk: A finance employee may send a firm message without knowing that the account team is negotiating a renewal or resolving a delivery issue.
A complete invoice automation workflow connects those facts. It starts with accurate billing data, sends the invoice through the right delivery channel, monitors status, triggers reminders based on actual conditions, provides a simple payment path, applies cash, and routes unresolved risk to the right human owner.
The market is investing in this operating model. The global AP automation market was estimated at USD 6.17 billion by 2025 and projected to reach about USD 11.17 billion by 2030, according to Quadient's AP automation statistics. But adoption figures also show why buying software isn't enough. Only 32.6% of invoices were processed without human intervention, while 14% required exception handling for errors or missing data, from the same source.
Operator's view: Automation isn't successful because an invoice enters a system. It's successful when clean invoices move without intervention and exceptions reach an owner with enough context to resolve them.
For a useful AP perspective on capture, validation, approval, and integration, finance leaders can review this invoice processing automation 2026 strategy. For the AR distinction and broader receivables context, see what AR automation means. The practical question is whether the firm is designing an end-to-end cash process or purchasing an isolated OCR feature.
Mapping Your Current Workflow and Designing Trigger Logic
Start with the workflow you have, not the workflow a software demo promises. Follow one invoice from creation or receipt through delivery, approval, follow-up, payment, cash application, and closeout. Record every system, person, spreadsheet, and handoff involved.
A useful map should answer five questions:
- Where does the invoice originate? Identify the billing system, project platform, CRM, ERP, or accounting file that creates the invoice.
- How does the client receive it? Note email, portal, electronic delivery, or manual sending, along with the address and contact role used.
- What confirms validity? Document checks against contracts, purchase orders, project records, approved time, milestones, and client-specific requirements.
- Who acts when something fails? Assign an owner for missing data, duplicate invoices, disputed charges, rejected delivery, and approval delays.
- What happens after payment? Define bank matching, remittance interpretation, partial payment treatment, unapplied cash, and client account updates.
The standard sequence is straightforward: invoice receipt, AI or OCR capture, validation, exception routing, approval, payment, and cash application. The complexity sits inside the rules. A professional services firm may validate a fixed-fee milestone against a contract rather than a purchase order, while a time-and-materials invoice may need approved time and expense records.
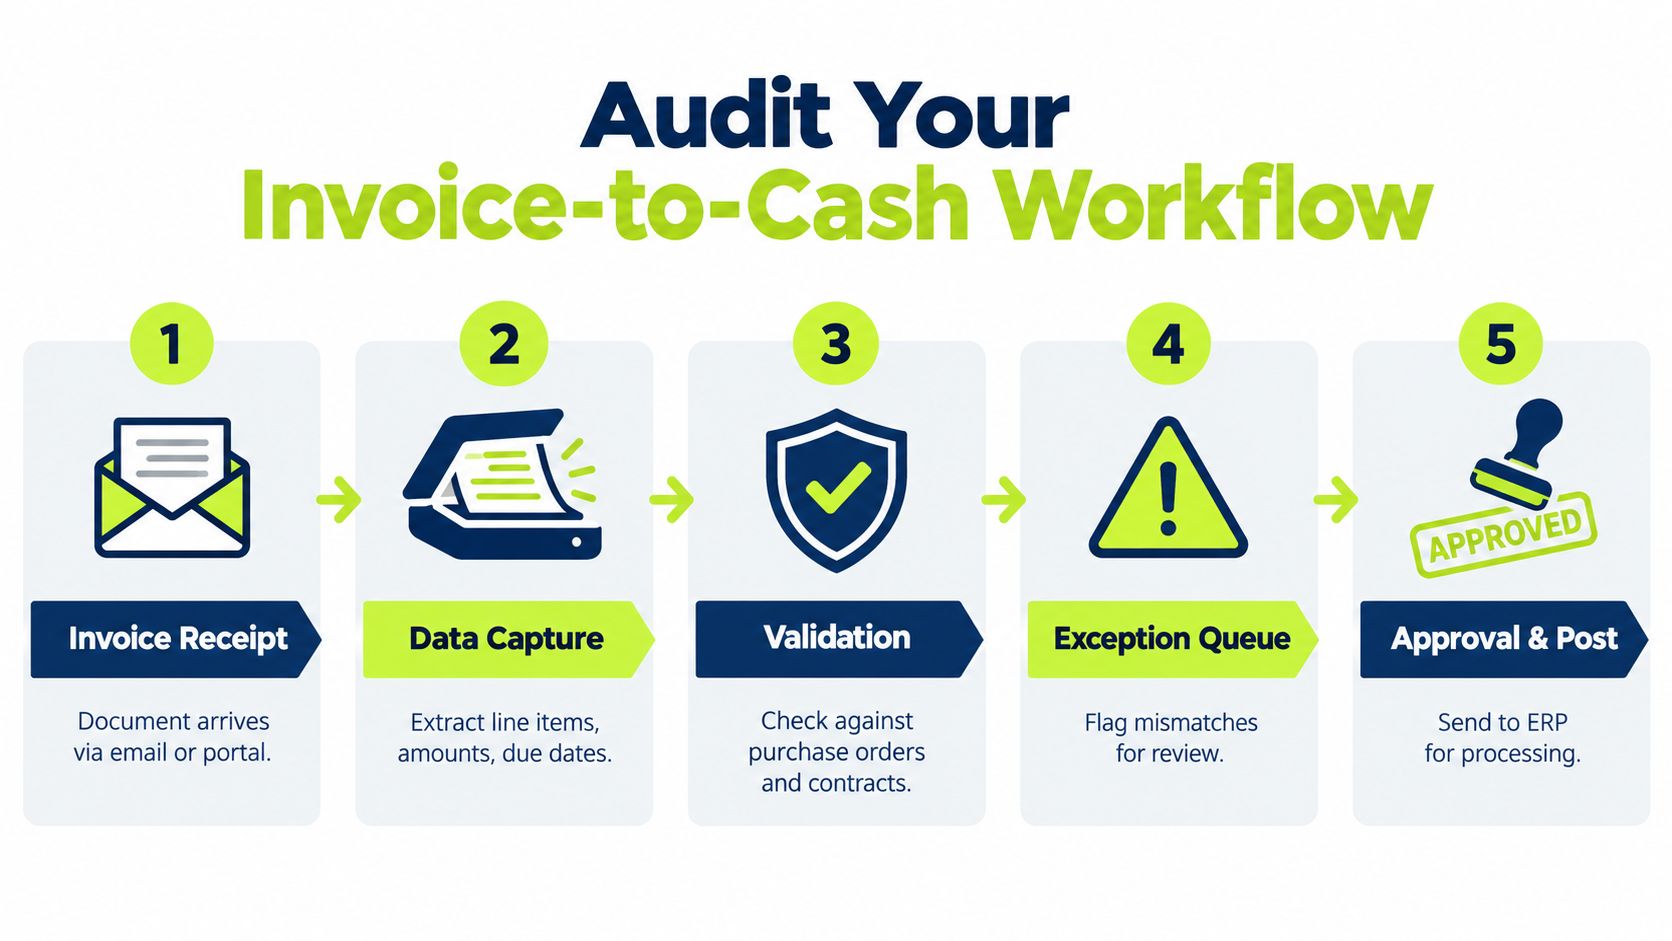
Build rules around exceptions
Don't send every invoice down the same approval path. Use amount, client, service line, project, contract type, and billing status to decide what can move straight through and what needs review.
Tolerance-based matching is important. A minor variance may be acceptable when the contract or purchase order allows it. A missing purchase order, conflicting legal entity, duplicate invoice number, or material amount mismatch should pause the record and route it to a named owner.
Duplicate detection should compare more than invoice number. Check the client, project, invoice date, amount, and source document. Near-duplicates often arise when a corrected invoice is uploaded without clearly marking the original as void.
Design triggers by business condition
A due-date trigger is only the beginning. Create rules for:
- Pre-due status: Confirm delivery and send a helpful payment reminder.
- Due-date status: Provide the invoice, payment link, and contact for billing questions.
- Early aging: Ask whether the client needs documentation, approval support, or a corrected invoice.
- Extended aging: Escalate internally to the account owner and collections owner.
- Risk signals: Increase review when the client has disputed prior invoices, changed payment contacts, or has a pattern of broken commitments.
Document the trigger, channel, message owner, suppression rule, and next action. Teams evaluating bespoke integrations can use AY Automate custom workflows as a reference point for the kind of process configuration required.
For approval design patterns, the approval workflows guide provides a useful internal reference. The principle is simple: automation should remove routine decisions, not hide unresolved decisions.
Building Omnichannel Outreach With Dynamic Billing and Payments
A reminder sequence works when it feels like a continuation of the client service experience. It fails when every customer receives the same message, regardless of invoice status, relationship, or reason for delay.
Begin with a clean billing record. The message should contain the invoice reference, amount, due date, project or engagement context where appropriate, billing contact, and a direct payment path. If the client needs a purchase order, tax document, or timesheet backup, the workflow should make that material easy to access.
QuickBooks Online can support a basic foundation by sending invoices automatically, tracking payments, and generating reports. Its reminder workflow can be configured for up to three scheduled reminder emails, such as 3 days before due, 1 day after, and 15 days after, as described in QuickBooks Online's accounts receivable automation guidance.
Match channel to the client
Email is usually the record of reference, but it isn't always the best channel for urgency. SMS can work for a short prompt when the client has opted into that communication method. A phone call is more appropriate when an invoice is materially aged, disputed, or blocked by an executive approver.
Use the CRM and accounting data to personalize the sequence:
- Known administrative delay: Keep the tone helpful and ask whether a document or coding detail is missing.
- Unanswered reminders: Move from email to a concise SMS or phone task for the account owner.
- Dispute signal: Suppress generic collections language and route the issue to finance and the engagement lead.
- High-value or strategic account: Give the relationship owner visibility before escalation.
The exact timing should follow the firm's terms and client preferences. Avoid hard-coding aggressive outreach that ignores weekends, holidays, active disputes, or a payment promise already recorded in the system.
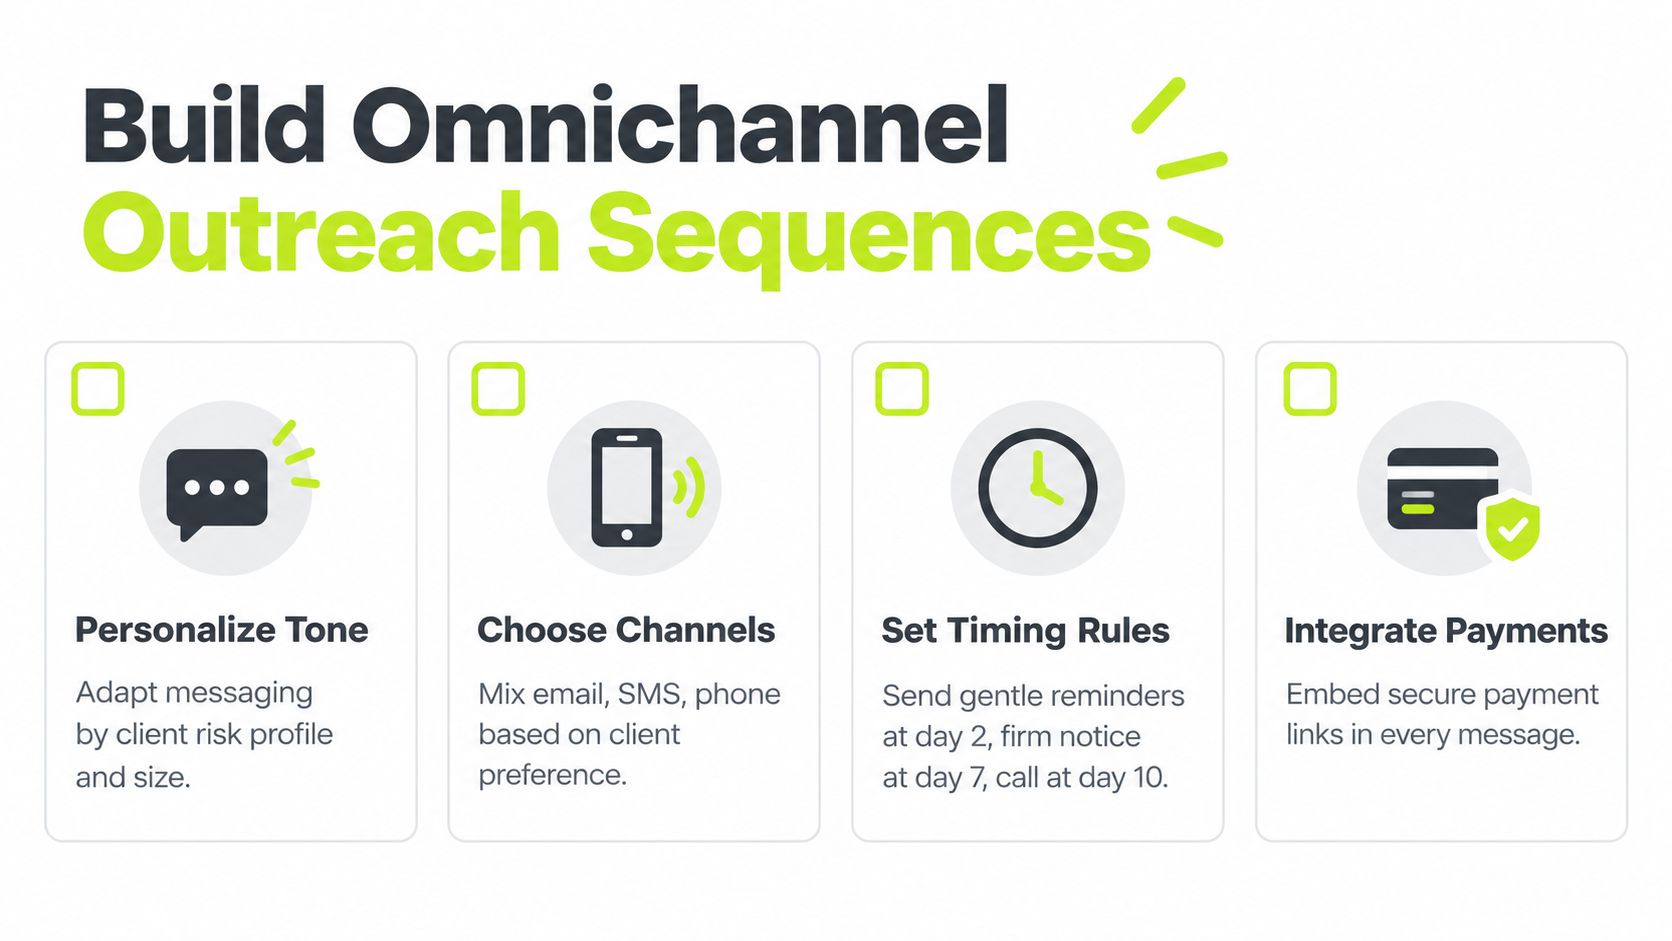
Remove payment friction
Every reminder should make payment easier, not merely ask for it. A dynamic billing experience can support recurring invoices, payment reminders, and a one-click online payment link inside the accounting workflow. More advanced setups connect live invoice and aging data to email, SMS, and phone outreach, then escalate as invoices move through aging buckets, as outlined in this QuickBooks AR automation workflow.
Payment options should reflect the client's normal process. Cards, bank transfers, and digital wallets can each remove a different obstacle, provided the payment portal records the invoice reference and returns usable remittance information.
A reminder without a payment path creates another task. A reminder with a clear payment path creates a decision.
Professional services firms should also connect billing to collections workflow rather than treating them as separate systems. Full-cycle AR automation commonly includes invoice creation, delivery, reminders, collections, and reconciliation, with the aim of reducing DSO and shortening billing cycles, as described by Versapay for professional services.
Automating Cash Application Exception Handling and Legal Escalation
Most invoice automation projects are judged at the front of the workflow, where data is captured and reminders are sent. The harder test comes after payment. If the system can't identify the invoice, interpret remittance, and reconcile the ledger, finance still carries the administrative burden.
Cash application should match payment information against invoice number, client, amount, bank reference, and available remittance detail. When the match is reliable, the system can apply cash and update the receivable. When it isn't, the payment belongs in an exception queue with enough context for a human to resolve it quickly.
A benchmark summary reported that manual invoice processing costs about USD 12.88 to USD 19.83 per invoice and takes around 14.6 days, while automated processing can reduce cost to about USD 3 or less. The same source reported throughput of roughly 23,333 invoices per FTE annually for fully automated AP teams, compared with 6,082 for a completely manual process, as documented in AP automation benchmark data.
Route exceptions with ownership
An exception queue is only useful when it has defined service ownership. Group exceptions by cause rather than displaying one undifferentiated list.
- Missing remittance: Assign to AR for client or bank detail follow-up.
- Partial payment: Assign to AR and the account owner when the client paid only part of the invoice.
- Duplicate or suspicious payment: Hold application until finance confirms the transaction.
- Invoice dispute: Assign to the engagement owner, with finance retaining the balance and aging context.
- Unapplied cash: Set a review deadline and require a documented reason for continued suspense.
The workflow should support autopilot and co-pilot modes. Autopilot can handle high-confidence matches and routine reminders. Co-pilot mode keeps a person involved when the invoice is disputed, the amount is unusual, the client is strategically important, or the data is incomplete.
Production designs should prioritize missing-field rules, duplicate detection, and tolerance-based matching before approval routing. A benchmarked workflow reduced average cycle time from 17.4 days to 3.1 days, raised touchless processing to 49.2% in best-in-class teams, and reduced cost per invoice to $2.78, according to AI invoice processing benchmarks. The same source noted that even average performers still had about 14% of invoices requiring human handling.
Escalate with judgment
Legal escalation shouldn't be the first automated response. It belongs after the firm has confirmed invoice delivery, checked for a valid dispute, documented previous commitments, and given the correct client contact a reasonable path to resolve the balance.
Use escalation logic that considers aging, amount, client risk, dispute status, and prior promises. The account owner should know what finance plans to send, while finance should retain control over the receivable record. A formal notice can use an authoritative legal voice when appropriate, but it must remain accurate, proportionate, and consistent with the firm's policies.
For the mechanics of matching receipts to open invoices and controlling unresolved balances, use cash application automation as a focused operating reference.
Integrating With ERP and CRM and Leading Change Without Disruption
Integration depth matters more than the number of features in a product brochure. A tool that captures invoices but doesn't synchronize invoice status, aging, payment activity, and customer ownership leaves the team with another system to maintain.
For an ERP-led finance stack, the priority is a reliable flow of master data, invoices, approvals, payments, and reconciliation results. The AR system should read the current receivable state and return completed actions without requiring staff to rekey updates.
A CRM-led model adds relationship context. It can identify the account owner, engagement status, renewal activity, client contacts, and active service issues. That context helps finance choose the right message and avoid escalating a balance while the commercial team is resolving a legitimate delivery concern.
QuickBooks-centric firms have a different decision. QuickBooks Online already supports automated invoice sending, payment tracking, reports, and scheduled reminders. The question is whether the firm needs additional orchestration across aging logic, outreach channels, payment escalation, and cash application.
Compare the operating options
Approach | What works | What breaks |
|---|---|---|
Accounting-only automation | Simple invoice creation, reminders, payment tracking, and reporting | Limited relationship context and weak exception ownership |
ERP-integrated workflow | Strong posting, controls, approval routing, and ledger synchronization | Can require more configuration and cross-functional ownership |
CRM-connected AR | Better personalization, account visibility, and coordination with delivery teams | Risk of fragmented financial truth if aging data isn't live |
Orchestration platform | Connects billing, outreach, payment, risk, and cash application | Requires clear rules, permissions, and integration governance |
The market gap supports this caution. One independent 2026 report said 75% of AP departments use some automation, but only 8% are fully automated and 68% still manually key invoice data into accounting systems, according to the State of Invoice Automation 2026 report. That isn't primarily an OCR problem. It points to incomplete process design and weak system connections.
Lead adoption as an operating change
Assign one process owner, one system owner, and one owner for each exception category. Give finance, sales, and delivery teams visibility into the next action, not just the outstanding balance.
Start with a limited workflow, such as one service line or client segment. Test invoice import, aging triggers, approvals, payment links, suppression rules, and cash application before expanding. The team should know what the automation does, what it never does without approval, and where to record a judgment call.
For broader context on how machine learning and automation fit inside finance systems, AI in accounting tools offers a useful comparison. The evaluation standard should remain practical: does the integration reduce duplicate entry and create one reliable view of the receivable?
Measuring Optimizing and Scaling Your Invoice Automation Workflow
A workflow becomes an operating system when the team can measure its behavior. Track the path from billing to cash, then separate routine performance from exception performance.
DSO, or Days Sales Outstanding, measures the average number of days between invoicing and cash collection. One published example calculates DSO at 30 days from $500,000 in receivables, $1,500,000 in credit sales, and a 90-day period, using the formula receivables divided by credit sales, multiplied by the period, as explained in this DSO guide.
Use DSO alongside operational measures:
- AR aging: Review balances by current status and aging bucket, then identify where invoices stall.
- Billing cycle length: Measure the time from work completion or milestone approval to invoice delivery.
- Touchless rate: Separate invoices that move without intervention from those requiring review.
- Exception volume: Track missing fields, duplicates, disputes, unapplied cash, and approval delays by cause.
- Recovery performance: Compare outreach outcomes by channel, client segment, and escalation stage.
- Cash application quality: Monitor unapplied balances and the time required to resolve them.
A 2025 survey cited in an independent AP analysis found only 4% of mid-market finance leaders had automated AP from invoice to payment with no manual touchpoints, while 48% reported little to no cost savings from tools they had already bought, according to Parseur's analysis of AI in accounts payable. The lesson for professional services firms is direct. Automating intake while leaving approvals, exceptions, and reconciliation manual won't produce the expected cash result.
Run a monthly optimization loop
Review the exception queue by root cause. If a large share of records needs the same missing document, fix the billing template or intake requirement. If approvals stall with one role, change the routing or delegation policy. If clients repeatedly pay without remittance, improve payment references and portal instructions.
Keep three artifacts current:
- A trigger register showing each event, message, channel, owner, and suppression rule.
- An exception playbook defining resolution steps and escalation responsibilities.
- A KPI dashboard connecting DSO and aging to workflow causes rather than reporting only the final balance.
Scale only after the first workflow is stable. Add client segments, service lines, and channels gradually, preserving human review where judgment protects the relationship.
For CFOs and Controllers, the target is not maximum automation. It's consistent billing, accurate follow-up, faster resolution, and clear control over cash. Resolut automates AR for professional services, consistent, accurate, and human.
Resolut connects invoice data, aging triggers, omnichannel outreach, payment options, cash application, and escalation workflows in one AR operating model. Visit Resolut to evaluate a practical way to reduce DSO, improve cash flow, and keep human judgment in the moments that matter.